How to create a home inventory, one room at a time
A simple way to list what you own, with photos, serial numbers and values, so an insurance claim after a fire, flood or break-in isn't a guessing game.
 The BoxTrack team · · 5 min read
Picture the adjuster sitting at your kitchen table a week after a kitchen fire, asking you to list everything that was in the cabinets. The pots, sure. The stand mixer. But the spice rack, the knife block, the second set of dishes in the high cupboard? Most people can name about half of what they own from memory, and the half they forget is the half they don't get paid for.
Knowing how to create a home inventory is mostly about doing it before you need it. It's a list of what you own, with enough detail and proof that an insurer can price it. It takes an afternoon or two the first time, and a few minutes a year after that. Here's how to do it without it turning into a project you never finish.
Why bother
State insurance regulators all say roughly the same thing. The California Department of Insurance says it's very important to take inventory of your belongings before you have a loss, and gives three reasons: you have a record of what you own and what it's worth, you have the serial numbers if something is stolen, and you can check whether your coverage is enough to replace it all.
That last one surprises people. Add up the contents of an ordinary house (furniture, clothes, electronics, kitchen, tools, the garage) and the total is often more than you'd guess. An inventory is the only way to know whether the personal property limit on your policy is realistic.
Start with the expensive things
If you only get partway through, make sure the part you finished is the valuable part. The Nevada Division of Insurance suggests starting with "big ticket" items: jewelry, art, collections, heirlooms and electronics. For each one, write down:
- what it is, with the brand and model
- the serial number, if it has one
- roughly when you bought it and what you paid
- its condition
- a photo, and a photo of the receipt or appraisal if you have it
The Connecticut Insurance Department also suggests attaching copies of receipts and appraisals to the inventory and noting model and serial numbers. For a laptop, a camera or a TV, the serial number is on a sticker on the back or bottom; photograph it rather than copying it out by hand.
Then go room by room
Once the valuables are done, walk the house one room at a time. Open every drawer and closet. A few things that help:
Take a slow video first. Stand in the doorway, then walk around the room narrating what you see. "Sofa, bought 2021. Bookcase, about 200 books. Record player and maybe 60 records." A ten-minute video of a room catches far more than you'd ever type.
Then photograph the details. Close-ups of anything worth more than a few hundred dollars, and of anything unusual that an adjuster wouldn't know the value of from a glance.
Count, don't itemize, the small stuff. Nobody needs 40 separate entries for your T-shirts. "T-shirts, about 40" and "Books, about 200, mostly hardback fiction" are what a claims adjuster will actually work with.
Don't forget the places you don't look. The California guide says to include closets, storage buildings, the attic and the garage. Connecticut adds the things you only use now and then, like holiday decorations and tools, and expensive items kept outside, like a swing set or garden sculpture. If you rent a storage unit, it counts too.
Here's a room order that keeps it manageable:
- Living room and dining room
- Kitchen (the one most people underestimate)
- Bedrooms and closets
- Bathrooms and linen closet
- Home office
- Garage, basement and attic
- Outside: grill, patio furniture, bikes, mower
Write down values you can defend
For each item or group, note what you paid and when, if you know it. If you don't, a fair estimate is better than a blank. Your policy decides whether you're paid the full cost of buying the item new or a depreciated value that takes age and wear into account, so check which you have. We cover that difference, and how it changes a claim, in home inventory for insurance.
Keep copies somewhere other than your house
An inventory that burns with the house is no help. Keep at least one copy off-site: in cloud storage, emailed to yourself, with a relative, or in a safe deposit box. Connecticut suggests a secure online location, a fireproof box or a safe deposit box, and the California guide suggests a copy away from home as well.
Keep it current
The guides disagree on how often. Connecticut suggests reviewing it once a year and whenever you make a significant purchase; California suggests three to four times a year. A good habit is to add big purchases the day they arrive (photograph the item, the serial number and the receipt) and to walk through the house once a year, maybe when you change the smoke alarm batteries.
Use an app if a spreadsheet won't happen
A spreadsheet works fine if you'll keep it up. Many people won't, which is why a phone app helps: you take the photos anyway, so the list builds itself as you go. The NAIC (the national association of state insurance regulators) offers a free Home Inventory app, and Connecticut's advisory recommends it.
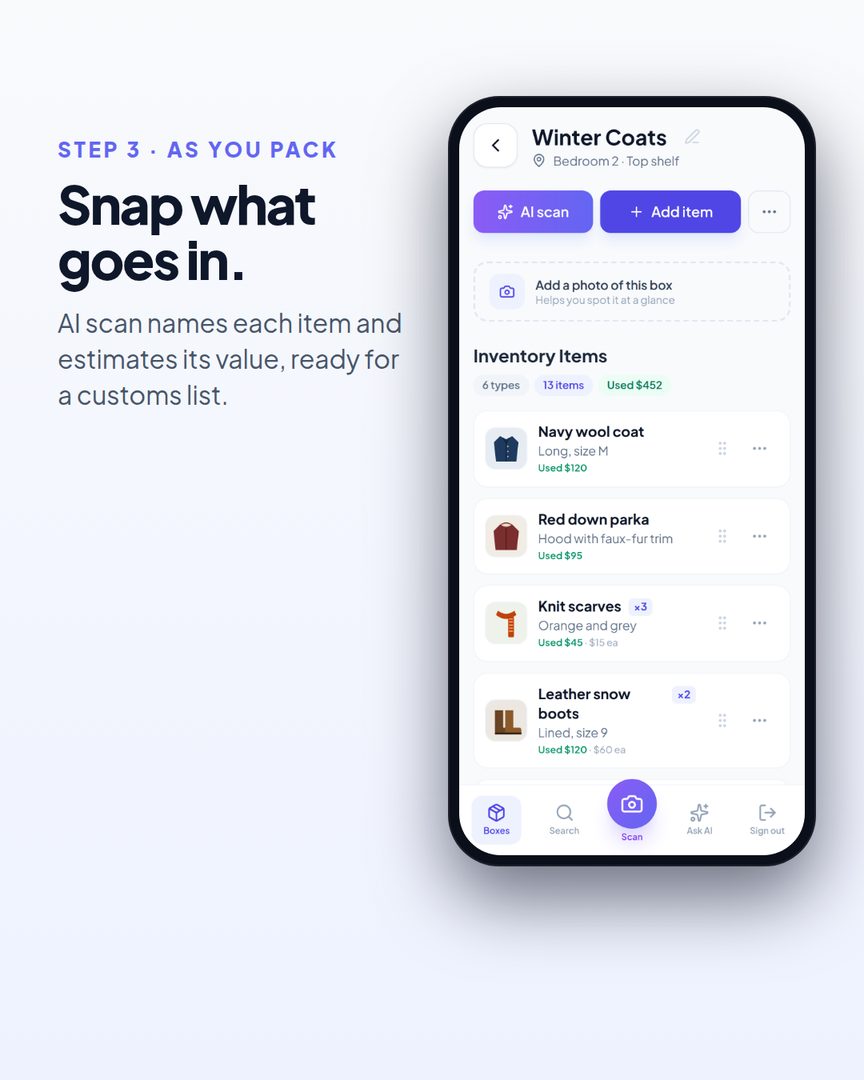
BoxTrack works for this too. Make a "box" for each room, closet or shelf, take a photo, and the AI scan lists what it sees with an estimated value you can edit. Add up to 10 photos per item for receipts and serial numbers, search everything from your phone, and export the whole list to Excel if you ever need it for a claim. See how BoxTrack works as a home inventory. Your first box is free.
If you're moving soon, it's worth doing both at once: the list you make while packing becomes your home inventory once you unpack. Our moving inventory guide shows how.
A one-afternoon plan
- First hour: valuables. Photos, serial numbers, receipts.
- Next two hours: a video walk-through of every room, closets and drawers open.
- Last half hour: save the video and photos to the cloud and email yourself a link.
- Later: fill in values and counts from the video, a room at a time, whenever you have twenty minutes.
That's enough to make a claim far easier than starting from memory, and you can fill in detail over the next few weeks.
Sources
- California Department of Insurance, Home Inventory Guide
- Nevada Division of Insurance, Home inventory
- Connecticut Insurance Department, Consumer advisory, April 4, 2025
This is general information, not insurance advice. Coverage and claim rules depend on your policy and your state; ask your insurer or agent what they need.