How to photograph your belongings for insurance
A room-by-room way to photograph and film what you own so the pictures actually help a claim, plus where to keep them so they survive.
 The BoxTrack team · · 5 min read
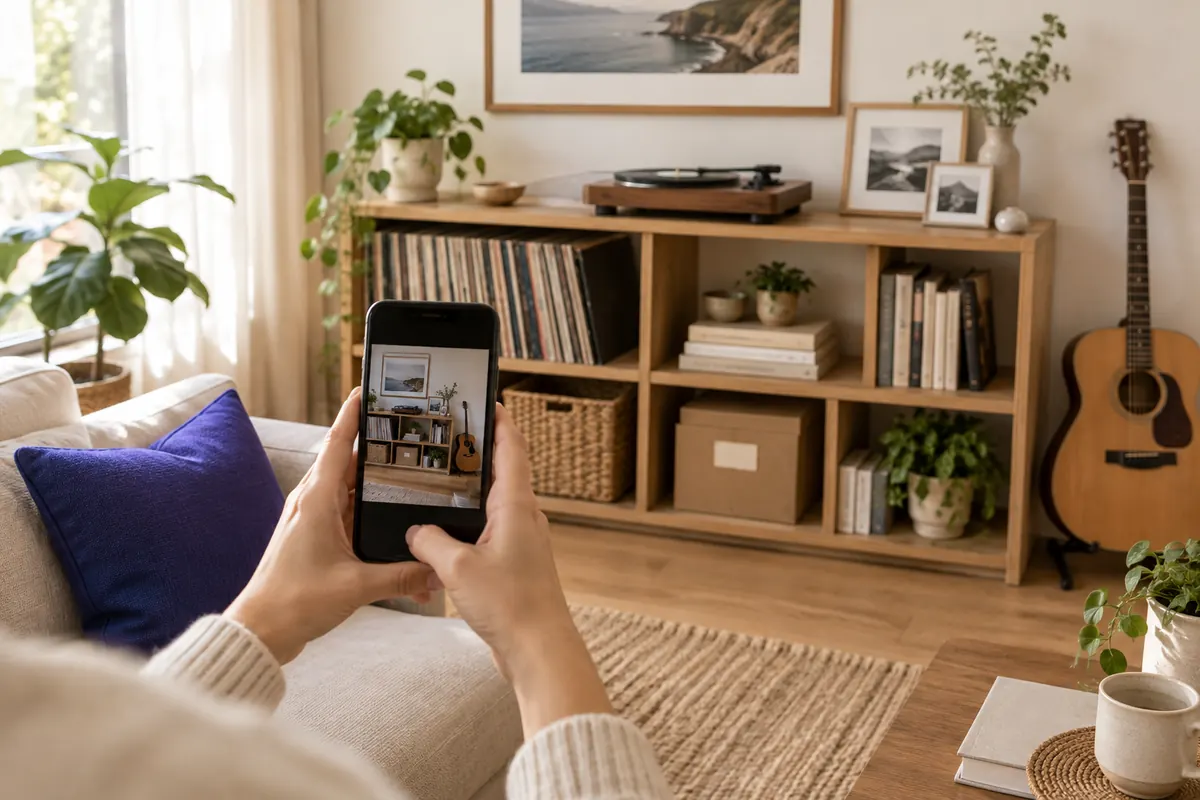
After the pipe burst, the adjuster asked for photos of the living room "before." There were plenty. Birthday parties, the dog on the couch, a Christmas tree. In every one, the TV was cut off at the edge of the frame, the bookshelf was behind somebody's head, and the stereo under the window never appeared at all.
Photos are the easiest proof you can give an insurer that you owned something and what shape it was in. Family photos almost never do that job. Photos taken on purpose, in an afternoon, do. Here's how to take them so they hold up.
What the photos need to show
State insurance regulators give the same advice in slightly different words. The Texas Department of Insurance says to photograph or film every room, open the closets and drawers, and record the serial numbers of appliances and electronics. The Nevada Division of Insurance adds receipts, appraisals and model numbers, and suggests keeping a copy somewhere other than your home. The University of California's home inventory guide recommends noting a description, purchase date, cost, model and serial number alongside the photos, and updating the record regularly.
In practice, each important item wants three things on camera:
- That it was there: the item in its place in the room
- What it is: the brand, model and serial number label
- What it was worth: the receipt, an appraisal, or at least the box or the order confirmation
You won't have all three for everything. Most things only need the first. Save the effort for the expensive ones.
The room-by-room method
Work one room at a time, always in the same order, so nothing gets skipped.
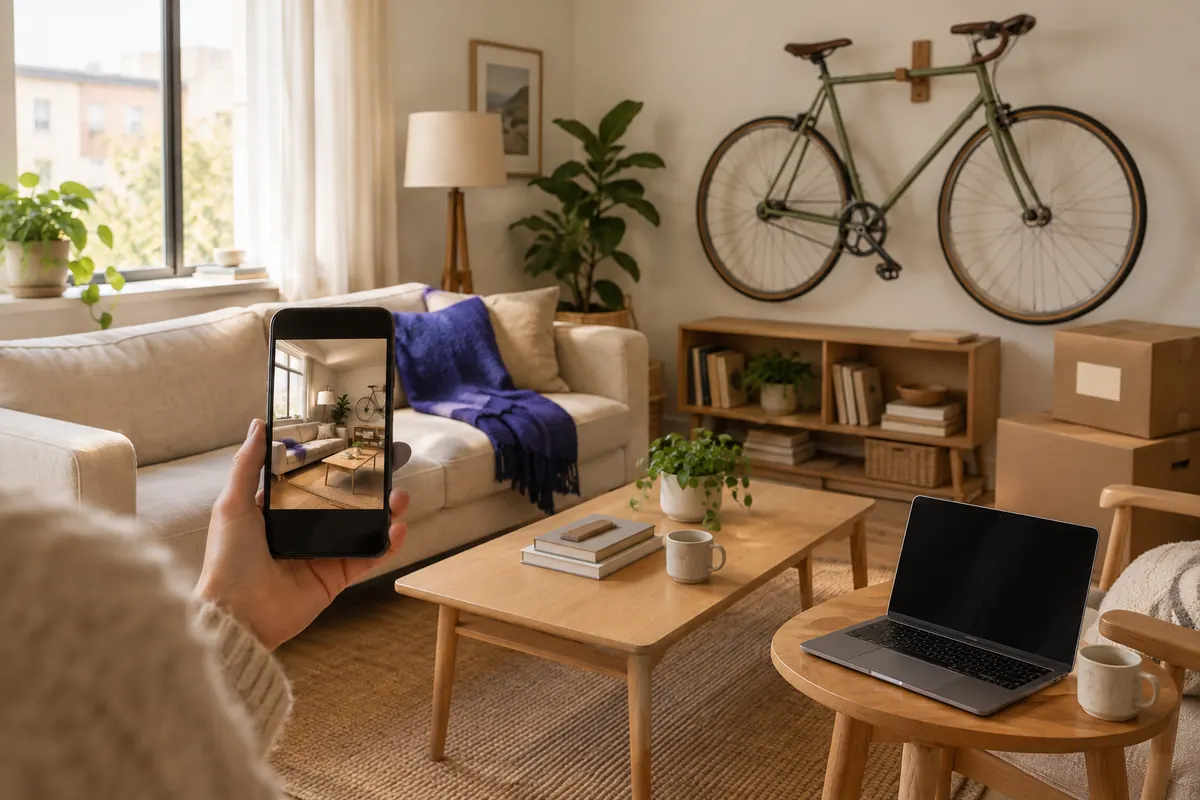
Start wide. Stand in a corner and photograph each wall, then turn and do the next. Four wide shots per room give the adjuster the whole picture: what was there, how it was arranged, roughly how nice it was.
Then medium. Get closer to each piece of furniture, each shelf and each cluster of things. A photo of a bookcase where you can read the spines is worth more than a wide shot where it's a brown rectangle.
Then close. For anything valuable, take a close-up of the item and one of its label. On a TV the label is usually on the back; on a laptop, the bottom; on appliances, inside the door or on the back panel. Jewelry, watches and collectibles get their own close-ups on a plain background.
Open everything. Closets, drawers, kitchen cabinets, the hall closet full of coats. What's inside adds up faster than the furniture does, and it's what people forget to list after a loss.
Don't skip the edges. Garage, attic, basement, shed and the storage unit across town all count. Tools, sports gear and seasonal decorations are expensive to replace and easy to forget.
Video is fastest, photos are clearer
A slow video walk-through of each room is the quickest way to capture a lot at once. Narrate as you go: "65-inch TV, bought 2023, about two thousand dollars. Sofa from the furniture store on Main, 2021." Your voice adds the details a picture can't, and the date is saved in the file.
But a frame from a video is often blurry, and you can't read a serial number off it. Do both: a video sweep for the room, and still photos for the valuable things and their labels.
| Video walk-through | Still photos | |
|---|---|---|
| Captures a whole room fast | ✓ | ✗ |
| Lets you narrate brand, age and price | ✓ | ✗ |
| Shows serial numbers clearly | ✗ | ✓ |
| Easy to attach to a claim item by item | ✗ | ✓ |
A few habits that make photos better
- Turn on the lights and open the blinds. A dark photo of a dark couch shows nothing.
- Wipe the lens. Phones in pockets get smudged, and a smudge turns every photo hazy.
- Photograph receipts flat on a table, in good light, so the store, date and total are readable. Do it the day something arrives, before the receipt fades.
- Keep the phone's date and location settings on for these photos. The timestamp helps show the items were there before the loss. Texas suggests labeling files with the date they were taken if your camera doesn't do it.
Keep the photos somewhere a disaster won't reach
Photos on a phone that's in the house when the house floods are no help. Back them up to a cloud account, and keep a second copy somewhere else: a relative's house, a safe deposit box, or with your insurance agent. Nevada's insurance regulator suggests exactly that: a copy online or in a fireproof box, and another with friends, relatives or your insurer.
Your photo inventory, in an afternoon
- First hourWide shots and a video sweep of every room
- Second hourMedium shots of shelves, closets and open drawers
- Third hourClose-ups and labels of anything valuable, then receipts
- Before you're doneBack everything up to the cloud and a second place
- Once a yearReshoot what's new and what's changed
Before a move, too
The same photos earn their keep on moving day. If a mover's truck delivers a dented dresser, a photo of it the week before is the best proof of what condition it left in. Photograph high-value pieces close up before the movers arrive. Our guide to full value protection vs released value explains how a mover's claim works.
Turn the photos into a list
Photos alone leave the adjuster to work out what's in them. A list that names each item, with its photo and value, is far easier to settle. Our guide to home inventory for insurance covers what an insurer asks for.
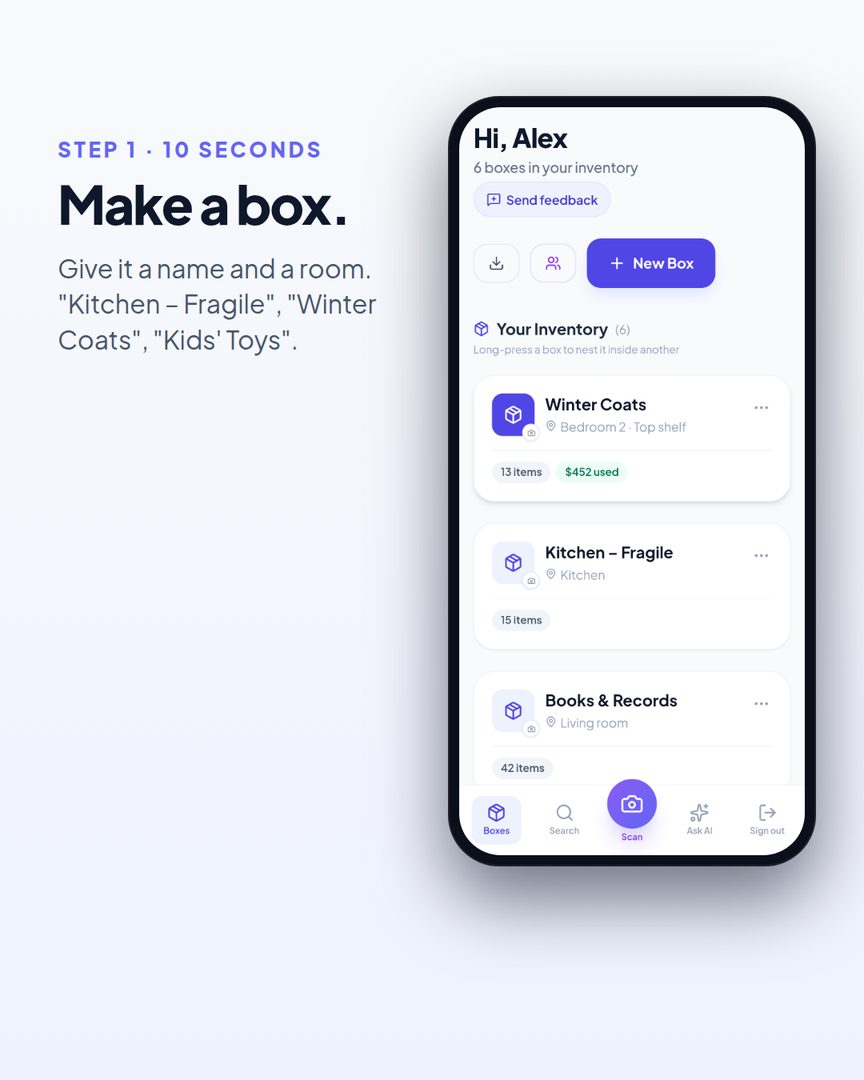
BoxTrack turns your photos into that list. Make a box in the app for each room, closet or bin, snap a photo, and AI lists the items in it with an estimated value for you to check. Add close-ups of serial numbers and receipts to each item. Everything is backed up to your account, and you can export the full inventory to Excel when a claim needs it. See how BoxTrack works for insurance records. Your first box is free.
Sources
- Texas Department of Insurance, Home inventory
- Nevada Division of Insurance, Home inventory
- University of California Agriculture and Natural Resources, Your home inventory (publication 8722)
This is general information, not insurance advice. Every policy is different, so ask your insurer or agent what proof they want for your coverage.